⬣ Fixed-Rate Growth Capital

Fixed-Rate Term Loans Built for Growth-Stage Operators

Deploy $50,000–$5,000,000 in fixed-rate capital for equipment, expansion, acquisition, or debt consolidation, and get two free strategist frameworks worth $594 the moment you apply.

No hard credit pull to pre-qualify. Not a lender: we connect you with independent financing partners.

20+ Years Capital Markets Experience $50K–$5M Term Loan Range No Hard Pull Pre-Qualification (888) 653-0124 Direct Line

Most Operators Only See One Offer

Term loan terms vary enormously by lender type. Without a positioning strategy and a way to compare structures, you take whatever the first lender quotes, often leaving real savings on the table.

Rate Spread Is Wide

Bank and SBA term loans run 7–15% APR. Online lenders range 12–35%. Applying to the wrong tier first can cost tens of thousands over the loan term.

Files Get Rejected on Presentation

Underwriters see hundreds of files. How you position revenue, use-of-funds, and repayment logic changes approval odds, before your credit score ever matters.

Stacking Mistakes Trigger Covenants

Layering a term loan on top of an existing line of credit without sequencing it correctly can violate covenants and trigger a call on your existing facility.

Three Steps From Application to Funded

The same process our team uses with every operator who comes through this page.

Step 1

Apply in Under 3 Minutes

Pre-qualification uses a soft credit pull and revenue history, and it will not affect your credit score.

Step 2

We Match You to Lenders

Your file is matched against bank, SBA, and online lending partners based on your revenue, time in business, and use of funds.

Step 3

Compare Offers and Close

Review rate, term, and structure side by side. Your two bonus guides arrive by email within one business day of applying.

What a Business Term Loan Actually Is

Before comparing offers, it helps to understand how a term loan is structured and why lenders treat it differently from revolving credit.

A business term loan delivers a single lump sum of capital up front, which you repay in fixed installments over a defined period, typically anywhere from one to ten years depending on the lender and the use of funds. The interest rate can be fixed or variable, and the repayment schedule is set at closing, so you know from day one exactly what your monthly obligation will look like for the life of the loan. This predictability is the main reason operators choose a term loan over other forms of financing when they have a specific, one-time capital need: buying equipment, opening a new location, acquiring another business, refinancing higher-cost debt, or funding a growth initiative with a clear return timeline.

Term Loans vs. Revolving Lines of Credit

The structural difference between a term loan and a business line of credit matters more than most applicants realize. With a line of credit, you're approved for a maximum limit and draw against it as needed, paying interest only on what you use, and the facility replenishes as you pay it down, much like a credit card. A term loan works differently: you receive the full amount at once, interest accrues on the full balance from day one, and once it's repaid, the loan is closed rather than reopened. That makes a term loan better suited to a single, well-defined capital project with a known price tag, while a line of credit tends to fit ongoing or unpredictable working capital needs like covering payroll gaps or seasonal inventory swings. Some operators use both together: a term loan for the fixed asset or expansion, and a business line of credit to smooth out day-to-day cash flow around it. If you're still deciding which structure fits your situation, our term loan versus line of credit comparison walks through the tradeoffs in more depth.

Common Uses for Term Loan Capital

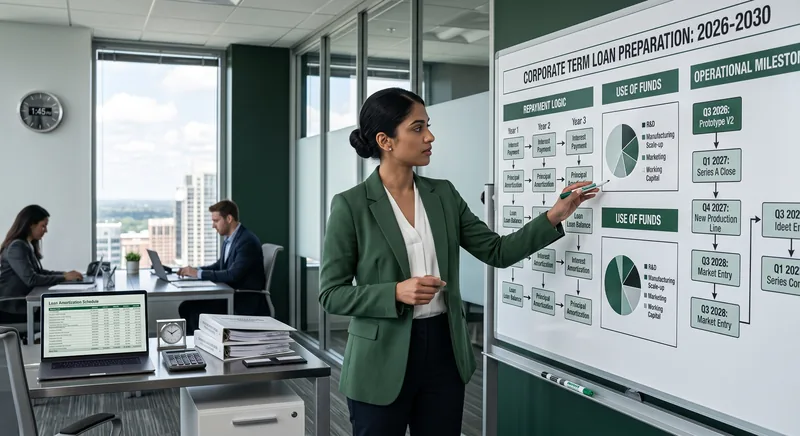
Operators typically bring a term loan file to us for a handful of recurring reasons: purchasing equipment or vehicles that will generate revenue or reduce operating costs, buying out a partner or acquiring a competitor, renovating or opening a new location, consolidating higher-interest debt into a single predictable payment, or funding a marketing or hiring push tied to a specific growth plan. Lenders generally want to see that the loan proceeds map to a concrete business purpose rather than a vague "general operating expenses" request, since a clear use of funds makes the repayment logic easier to underwrite.
What Underwriters Actually Look At

Every lender's checklist looks a little different, but the underlying questions they're answering are consistent across bank, SBA, and online term loan products.

Cash Flow

Can You Service the Debt

Underwriters model your existing revenue and expenses against the proposed monthly payment to confirm there's enough cushion to cover it even in a slower month, not just an average one.

Time in Business

Track Record Matters

A longer operating history gives underwriters more data points to model against, which is why newer businesses often see tighter terms or smaller amounts until they build a longer track record.

Existing Debt

Current Obligations

Lenders review what you're already carrying, including any outstanding line of credit balances, equipment financing, or merchant cash advances, to see how much additional debt service your revenue can reasonably absorb.

Use of Funds

Why You're Borrowing

A clearly articulated, specific use of funds, tied to a measurable business outcome, reads very differently to an underwriter than a vague request, even when the credit profile is identical.

Collateral

What Secures the Loan

Some term loans are secured by the equipment or asset being financed, real estate, or a general lien on business assets, while others rely primarily on a personal guarantee. Collateral position affects both approval odds and pricing.

Credit Profile

Business and Personal

Most lenders review both business credit history and the owner's personal credit, particularly for smaller companies where the two are closely linked in the underwriter's eyes.

Not Sure You'll Qualify Yet?

Pre-qualification uses a soft pull, so you can see indicative terms before deciding how to position your file.

Check Capital Eligibility →

How to Prepare a Strong Application

The operators who move fastest through underwriting are the ones who show up prepared, not the ones with the highest credit score.

Organize Your Financials First

Have recent bank statements, profit and loss statements, and tax returns ready before you apply. A complete, organized file moves through underwriting faster than a partial one that requires back-and-forth requests.

Write a Clear Use-of-Funds Statement

Spell out exactly what the capital will be used for and how it connects to revenue growth or cost reduction. Specificity signals to an underwriter that you've thought through the plan, not just the ask.

Know Your Numbers Cold

Be ready to speak to your monthly revenue trends, existing debt payments, and margins. Lenders and their underwriting teams move faster with applicants who can answer questions about their own business without hesitation.

Check Your Existing Debt Structure

Review what you're currently carrying before applying for a new term loan, especially if you have an open working capital facility or line of credit, so you understand how a new fixed payment fits alongside it.

Match the Loan Type to the Need

A shorter-term need might be better served by working capital financing, while a long-lived asset purchase fits a traditional term structure. Reviewing our term loan qualification guidelines before applying can help you gauge whether this is the right product for your situation.

Understand the Full Process Timeline

Knowing what happens at each stage, from initial application to funding, helps you plan around it. Our step-by-step application process breakdown covers what to expect at each stage in more detail.

Managing the Loan Once Capital Arrives

Getting funded is the beginning of the relationship with your lender, not the end of the process.

Once funds are disbursed, set up automatic payments if your lender offers them, so a fixed obligation never becomes a missed one due to an oversight. Track how the capital is actually being deployed against the use-of-funds plan you presented during underwriting; if your plans shift, most lenders would rather hear from you proactively than discover a change after the fact. Keep your financial records current even after closing, since a strong track record on this loan becomes part of the file for your next round of financing, whether that's a second term loan, a line of credit, or a refinance into better terms as your business grows.

When a Term Loan Makes More Sense Than the Alternatives

A term loan tends to be the right fit when you have a defined capital need with a clear dollar amount and a start date, when you want the predictability of a fixed payment for budgeting purposes, and when the return on the capital, whether through new equipment, an acquisition, or expansion, plays out over a timeline that matches or exceeds the loan term. If instead your need is recurring or unpredictable, such as smoothing out cash flow between invoice payments or covering seasonal swings in inventory, a revolving line of credit is usually the better structural fit since you only pay for what you actually draw. Many growth-stage operators end up using both at different points, which is why understanding the structural differences up front, before you apply for either, tends to produce a better outcome than defaulting to whichever product a single lender happens to pitch first.

Two Strategist Frameworks, Free

Written by our Chief Credit Strategist for operators preparing a term loan file, yours at no cost when you complete an application.

The FUNDABLE Positioning Framework cover
$297 Value

The FUNDABLE Positioning Framework

A step-by-step method for presenting revenue, use-of-funds, and repayment logic the way underwriters actually want to see it, before they ever pull your file.

The Strategic Loan Stacking Playbook cover
$297 Value

The Strategic Loan Stacking Playbook

How to sequence a term loan alongside an existing line of credit or future financing without tripping covenants or triggering a call on your other facilities.

$594 Total Value

Delivered by email within 1 business day of a completed application. No separate purchase required.

See What You Qualify For in Under 3 Minutes

No hard credit pull. Revenue history is what qualifies you, not just your FICO score.

Check Capital Eligibility →

Business Term Loan Questions

What is a business term loan?

A lump-sum of capital repaid over a fixed schedule at a fixed or variable rate, used for equipment, expansion, acquisition, or debt consolidation. Unlike a revolving line of credit, funds are disbursed once and repaid on a set amortization schedule.

What interest rates should I expect?

Bank and SBA term loans typically run 7–15% APR for qualified borrowers. Online lenders range 12–35% depending on time in business, revenue, and credit profile.

How much can I qualify for?

Most operators on this program qualify for $50,000 to $5,000,000, sized to monthly revenue, time in business, and existing debt service.

How do I get the two free bonus guides?

Complete the application through our secure partner link above. Our team emails both guides to the address on your application within one business day.

How long does approval take?

Online lenders in our network typically respond in 1–5 business days. Bank and SBA-backed term loans take 2–6 weeks in exchange for lower long-term cost.

Will applying hurt my credit score?

Pre-qualification uses a soft credit pull, which does not affect your score. A hard pull only occurs if you move forward with a formal offer from a specific lender.

Ready to Apply for Your Term Loan?

Meridian Private Line connects operators with independent financing partners. Not a lender. Affiliate partnerships present.

Check Capital Eligibility →

You Finished This — Add as Preferred Source

Add as Preferred Source

Affiliate Disclosure: This page contains affiliate links. We earn compensation when you click links to lender partners. This does not affect your rates or terms. Full disclosure.

Meridian Private Line is not a lender and does not make credit decisions. Bonus guides are educational materials, not financial or legal advice.